2026-09-28 · 5 min read
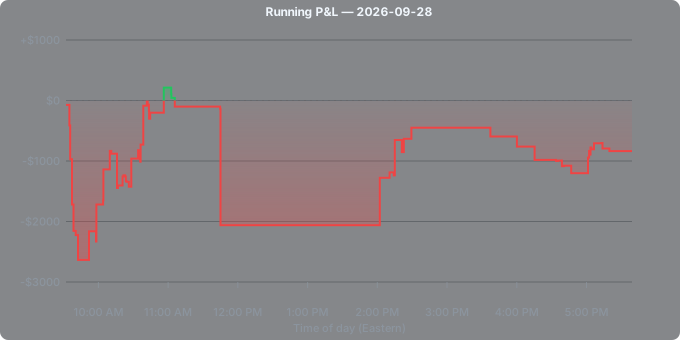
Session edge, AI coach verdict, and running P&L for 2026-09-28.
Trim Review
How much of today's result was carried by a few outliers? The table recomputes the core session stats with the biggest movers removed. Trimmed rows are colored vs baseline: green = holds most of the move, amber = meaningful erosion, red = collapses or flips sign.
| Scenario | Trades | Net P&L | Total R | E[R] / trade | $ WR | PF |
|---|---|---|---|---|---|---|
| Baseline (all trades) | 64 | −$836.63 | -0.88R | -0.014R | 42.2% | 0.89 |
| − single best + single worst | 62 | +$304.58 | +0.32R | +0.005R | 41.9% | 1.05 |
| − top 4 + bottom 4 (≈5% each tail) | 56 | +$339.87 | +0.36R | +0.006R | 41.1% | 1.09 |
Trimmed trades: Single best + single worst — removed KNRX +$782.77 (best) · KNRX −$1923.98 (worst). Top 4 + bottom 4 — removed 4 from each tail (by $ P&L).
Outlier-driven red session: without the worst trade (or the bottom 5%), the rest of the book was roughly flat-to-green. The damage was concentrated — underlying behavior was fine.
Session verdict
{"dayVerdict":"KNRX did almost all the offering today: +401.6% from its $0.319 open to a $1.600 high at 2:01pm, across 15 halts, and it still held 71% of that move into the close at $1.230. You took 31 positions in it for +$1.11k gross — 16 wins against 15 losses, with your best entry at 2:02pm (+$783, essentially at the high) and your worst at 11:45am (-$1.92k, a red entry well below the eventual high with the stock already 30+ minutes into its most volatile stretch).
Net-net you captured a real share of the day's single biggest mover, but the swing between +$783 and -$1.92k on the same name shows the offering and the damage came from the same source: repeated high-frequency entries into a stock that kept halting and re-extending.
MSGY was the other clean win: only two positions, both after the 8:39am high of +13.1% from the open, for +$1.06k combined (+$643 at 10:38am, +$415 at 10:56am) — a stock that gave back the entire move and then some, closing -62.7% versus its open, yet you were profitable on both entries taken after that high had already printed. That is a real result extracted from a stock that ultimately became a loser for anyone still holding it into the close.
Everything else on the day was a drag. NAMI cost you $2.49k on five positions, all entered in a seven-minute window (9:35-9:42am) before or right at its 9:42am high of +15.9%, on a stock that only closed +8.6% off the open and had given back 54% of its move — a name that never offered enough distance to justify five separate entries.
KNDI (-$314, all three losers), SOAR (-$129, 2-6 on the day), YMT (-$218) and NIVF (-$220) were all thin or negative offerings — SOAR moved +23.6% intraday but gave back 67% of it, YMT moved barely 1%, and NIVF gave back its entire +10.5% move and more. None of these were shapes worth the position count you put on them.
Across the seven runners you skipped, four moved +30% or more from the open (two of those +50%+, the largest +83%), and none of the +30% movers held even half their move into the close — so the opportunity cost sits mainly in names that would have faded on you anyway, not a missed holder.
Looking at the broader pattern across the last week, the runners that kept the most of their move — MSGY on 9/25 held 64% of a +436% move, R9 held 58% of +101% — tended to make their highs later in the session (after 11am), while names making highs in the premarket or first half hour more often gave most or all of it back: R2, R3, R6, and R7 all made highs before 7am and closed with negative retained percentages. Today's KNRX fits the holder profile exactly — a 2:01pm high retaining 71% — while NAMI (9:42am high, -54% retained) and NIVF (7:02am high, -100% retained) fit the fader profile precisely, and your dollars split the same way: profit in the late-high holder, losses in the early-high faders.
Against your own validated lanes, the split is stark: the 32 positions with 2+ halts before entry made +$1.69k, against -$2.65k on the 32 positions with fewer than 2 halts — almost the entire day's deficit sits in the halt-light group. Within the halt-heavy group, the 13 positions held 30 seconds or longer in the A+ lane made +$913, while the 19 positions scalped under 30 seconds in that same halt-heavy setup — a validated DONT lane — still made +$775 today despite being a historically -3.5-per-$1k pattern.
The nine sub-$1 scalps under 30 seconds, another DONT lane, were flat at +$71. The lane data says your edge lives in staying in halt-heavy names past the first 30 seconds, not in the quick in-and-out around them."}