2026-09-16 · 5 min read
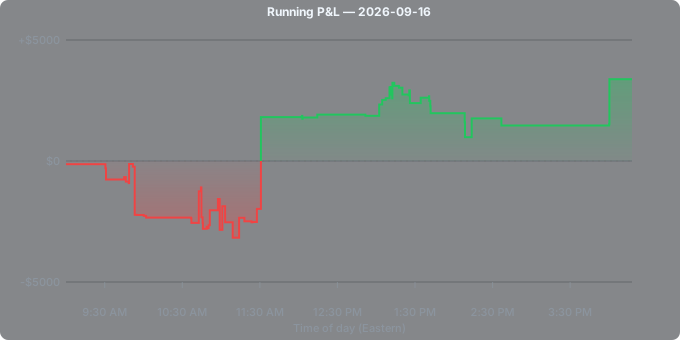
Session edge, AI coach verdict, and running P&L for 2026-09-16.
Trim Review
How much of today's result was carried by a few outliers? The table recomputes the core session stats with the biggest movers removed. Trimmed rows are colored vs baseline: green = holds most of the move, amber = meaningful erosion, red = collapses or flips sign.
| Scenario | Trades | Net P&L | Total R | E[R] / trade | $ WR | PF |
|---|---|---|---|---|---|---|
| Baseline (all trades) | 67 | +$3381.11 | +4.15R | +0.062R | 45.5% | 1.29 |
| − single best + single worst | 65 | +$1571.22 | +1.93R | +0.030R | 45.3% | 1.16 |
| − top 4 + bottom 4 (≈5% each tail) | 59 | +$610.80 | +0.75R | +0.013R | 44.8% | 1.09 |
Trimmed trades: Single best + single worst — removed DLXY +$3794.95 (best) · RETO −$1985.06 (worst). Top 4 + bottom 4 — removed 4 from each tail (by $ P&L).
Top-heavy green session: most of the P&L came from a handful of outsized trades; the broader distribution was only modestly plus-EV. Real but concentrated edge.
Session verdict
{"dayVerdict":"DLXY and MEDS carried this day, and you priced both of them well relative to what they offered. DLXY ran from an open of $1.02 to a high of $4.45 at 12:40pm — a 336% move — and even though the stock gave most of it back to a last price of $2.03 (29% of the move retained), you took +$4.69k gross out of 10 positions, with the largest single win of the day, +$3.79k, on an 11:30am entry that held for 6,622 seconds through 4+ halts.
MEDS offered a similar shape: open $4.035 to a 10:58am high of $12.31 (+205%), retaining just 24% of that at $6.06, and you extracted +$3.73k across 15 positions, 12 of which were entered before the high was even made — real anticipation, not chasing. SNYR, by contrast, moved just as violently in percentage terms (open $0.142 to $0.64, +351%) but you only cleared +$614 across 15 positions there, with 10 of those 15 entries coming after the 1:11pm high — you were mostly buying the fade on that one rather than the move.
RETO is the outlier that cost you the day's biggest single loss and a large chunk of gross. It ran from $4.52 to $14.62 (+223%) at 11:27am, then collapsed to $1.83 by the close-of-data mark — a full round trip, -27% of the open-to-high move retained, meaning it gave back more than it ever offered net of the open.
All 13 of your entries came before that 11:27am high, and all 13 came after the first of its 8 halts at 9:36am — you were buying into the halts on the way up, and the reversal after the high erased -$5.15k gross, including the day's largest loss of -$1.99k at 9:53am. ZTG and GMEX were smaller but told the same story in miniature: ZTG's high was actually made premarket at 7:25am, and by the time your 3 entries landed at 9:30-9:31am, all after the high, the stock was already down -48.5% versus the open with -85% of its move retained — a name you caught entirely on the wrong side.
Across the smaller positions — LESL, QCLS, GSUN, FTFT, PDSB, BENF — you took small, mostly matched-to-size pieces of moves that ranged from 39% to 370%, netting modest gains or near-breakeven results; nothing there moved the day much either way. Only 1 runner went untraded today, and it moved +96.5% while giving back all of it by the close — you were effectively in front of nearly the entire list, so today's result is about execution on names you already had, not missed opportunity.
Across the trailing week, the pattern in what holds versus what fades keeps showing up around float and halt count together. FTFT's 9/14 session, with just 1 halt, retained 77% of a 187% move into the close, while RETO today, with 8 halts and a much larger float (32.9M versus FTFT's 0.4M), gave the whole move back and then some.
MEDS across three sessions (9/9, 9/15, 9/16) has retained 24-36% of its move each time, with 2M-2M float and 2 halts most days — a consistent partial-holder, and you've been in it every time. DLXY and QCLS, both today, sit in the extreme-halt bucket (31 and 21 halts respectively) and both retained around 29-30% of their moves, in line with SNYR's 27% on 1 halt — high halt counts here are tracking with partial, not full, retention, and your trading matched that reality rather than expecting a clean hold.
Your own validated lanes back this up directly: positions with 2+ halts before entry held 30 seconds or longer — an A+ lane at +10.9 per $1k historically — made +$2.34k today across 11 positions, and includes your DLXY and MEDS winners. The 4+-halts-before-entry lane, A at +4.4 per $1k, contributed +$1.60k across 14 positions.
Against that, the DONT lanes cost you: 13 positions with 2+ halts before entry scalped under 30 seconds lost -$1.18k, and 14 sub-$1 scalps held under 30 seconds lost -$180 — these overlap heavily with the RETO entries that got hit on the reversal. The split is clean: when you let the halt-heavy names breathe past 30 seconds, you were paid; when you scalped the same setups fast, you paid the market instead."}