2026-11-06 · 5 min read
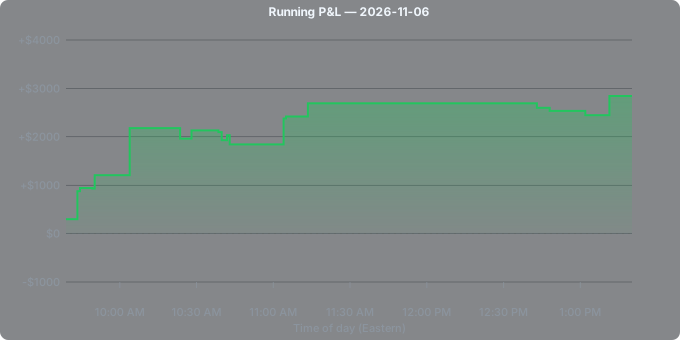
Session edge, AI coach verdict, and running P&L for 2026-11-06.
Trim Review
How much of today's result was carried by a few outliers? The table recomputes the core session stats with the biggest movers removed. Trimmed rows are colored vs baseline: green = holds most of the move, amber = meaningful erosion, red = collapses or flips sign.
| Scenario | Trades | Net P&L | Total R | E[R] / trade | $ WR | PF |
|---|---|---|---|---|---|---|
| Baseline (all trades) | 20 | +$2843.42 | +2.92R | +0.146R | 57.9% | 4.27 |
| − single best + single worst | 18 | +$2087.43 | +2.15R | +0.119R | 58.8% | 4.20 |
| − top 1 + bottom 1 (≈5% each tail) | 18 | +$2087.43 | +2.15R | +0.119R | 58.8% | 4.20 |
Trimmed trades: Single best + single worst — removed SOXL +$972.63 (best) · RAYA −$216.64 (worst). Top 1 + bottom 1 — removed 1 from each tail (by $ P&L).
Note: at this session size the 5% tails round to a single trade each, so the two trim rows converge to the same numbers. They diverge on busier sessions (≥ 20 trades).
Broad green session: still clearly green after trimming the biggest movers, so the day was a stack of small plus-EV decisions compounding — not a few home runs.
Session verdict
RAYA was the day's big mover and you were all over it: 13 positions for +$1.35k gross. The stock opened at $1.130, ran to a high of $2.125 (+88.1%) at 9:51am, then gave it all back and then some, closing at $0.8442, 29% underwater versus the open.
Only 3 of your 13 entries came before that 9:51am high, with 10 coming after — yet seven of the thirteen were winners, including the +$578 entry at 9:43am right into the run, and the worst was -$217 at 10:23am chasing a move that was already 30%+ off its high. That's a real share of a move most people would have only caught on the way up; you were still finding money on the way down.
OMH offered less in your hands but you took it clean: one position at 1:11pm ET for +$397, on a stock that had already made its high of $14.99 (+49.9% from a $10.00 open) at 4:16am and closed down 26.4% versus the open with only 47% of the move retained. Your single entry came after a sixth halt in the session (6 total, the last three clustered between 12:59pm and 1:13pm) — you picked up a late, clean scalp out of a name that had already spent most of its real move and was mostly chop by the time you touched it.
VIVK gave you +$365 on two quick entries at 9:38am and 9:44am, right around its 9:44am high of $0.9496 (+16.3%) — a stock that ultimately closed down 39.2% from the open and gave back the entire move, but you were positioned on the right side of it before the reversal. STAK was your one clean miss: all three of your entries (12:43pm-1:01pm) came before the stock's actual high of $3.29 (+60.5%) at 3:57pm, and it held 98% of that move into the close at $3.260 — you lost $246 on a name that ended up being the best closer of the day, just hours before the real move happened.
Of the three runners you didn't trade today, two moved 30%+ from the open (one 50%+, topping out at +80.5%), and one of those 30%+ movers still held over half its move at the close — modest opportunity cost on a day where your traded names already captured the bulk of what was available.
Looking at the last week of runners, the retention split keeps tracking halt activity and timing more than anything else: multi-halt names with afternoon highs (STAK at 3:57pm today holding 98%, and another multi-halt name on 11/5 that held 71% of its move after 8 halts) tend to keep their moves, while pre-market or early-morning toppers bleed hard — OMH's 4:16am high here held just 47%, and several other pre-market-high names across the week closed giving back 50% or more. RAYA and VIVK both fit the fade profile exactly: early highs (9:51am and 9:44am) that gave back the entire move and then some, and you traded both correctly as scalps rather than holds.
STAK was the one name in your day that matched the hold-the-move profile, and it's also the one you sold out of hours before its move actually happened.
Your playbook data lines up with the day's dollars. The five positions with 2+ halts before entry made +$1.30k, versus +$547 across the other fourteen; the three positions you held 30+ seconds after 2+ prior halts (an A+ lane, +$10.0 per $1k historically) made +$970 today, while the two positions that fit the DONT lane for sub-$1 scalps under 30 seconds only mustered +$330.
The four positions sitting in validated A/A+ lanes with no DONT exposure made +$1.55k combined, more than the entire day's gross — the two positions that touched a DONT lane still finished positive at +$330, but well below what the A-lane trades returned per position.