2026-11-02 · 5 min read
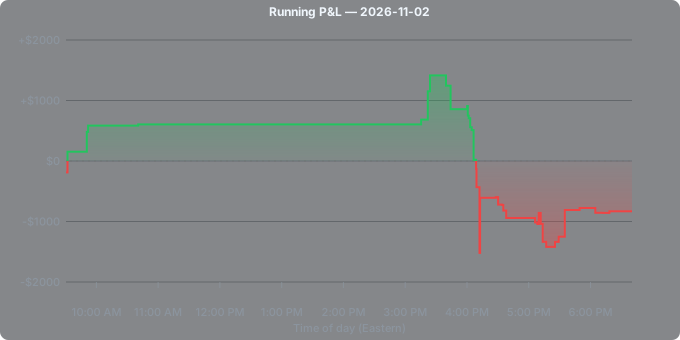
Session edge, AI coach verdict, and running P&L for 2026-11-02.
Trim Review
How much of today's result was carried by a few outliers? The table recomputes the core session stats with the biggest movers removed. Trimmed rows are colored vs baseline: green = holds most of the move, amber = meaningful erosion, red = collapses or flips sign.
| Scenario | Trades | Net P&L | Total R | E[R] / trade | $ WR | PF |
|---|---|---|---|---|---|---|
| Baseline (all trades) | 38 | −$831.05 | -0.87R | -0.023R | 42.1% | 0.81 |
| − single best + single worst | 36 | −$654.81 | -0.69R | -0.019R | 41.7% | 0.79 |
| − top 2 + bottom 2 (≈5% each tail) | 34 | −$631.19 | -0.66R | -0.020R | 41.2% | 0.76 |
Trimmed trades: Single best + single worst — removed VCIG +$910.19 (best) · VCIG −$1086.43 (worst). Top 2 + bottom 2 — removed 2 from each tail (by $ P&L).
Broad-based red session: the loss is still there after trimming the biggest movers — this wasn't one bad trade, it was the whole book tilted the wrong way.
Session verdict
{"dayVerdict":"VCIG is the whole story of this session. The stock ran from an open of $3.39 to a high of $9.29 at 3:24pm — +174% — and still closed at $8.16, holding 81% of that move, after ten halts between 12:30pm and 3:45pm.
You took 19 positions in it between 3:15pm and 4:38pm, 17 of them after the 3:24pm high, and came out -$1.42k gross, including the session's largest win (+$910 at 4:12pm) and largest loss (-$1.09k) at the exact same 4:12pm entry time. A stock that held 81% of a +174% move is about as clean a holder as this market produces, and the dollars still went the wrong way — this wasn't a case of the stock fading on you, it was a case of entries that didn't line up with a move the stock was actually sustaining.
Everything else you traded that day was smaller in scale but better matched. RBNE offered +69.8% to a 9:53am high before giving essentially the whole move back (-28% retained, closing -19.7% under the open); both of your two entries came before that high, at 9:50-9:51am, and you walked away +$432 — you caught the top of a stock that ultimately surrendered the entire move.
CLRO ran +10.7% to a 9:33am high and then gave back the whole move and more (-15.5% close vs open), yet your two entries, also both pre-high, netted +$153. INLF moved +39.3% to a 10:42am high and held 44% of it into the close; all five of your entries came after that high, between 5:35pm and 6:18pm, and you still finished +$420.
SGRX (+40.5% to a 9:40am high, 54% retained) and PARA (+17.4% to a 4:28am high, then a full giveback, -36% close vs open) both cost you money on post-high entries, -$99 and -$380 respectively, and BDMD and WETO were small, each entered after their highs for token gains. Strip out VCIG and the rest of the day nets to roughly +$592 gross on moves that were mostly modest — this was a day where the small, honest moves were captured reasonably well and the one outsized mover ate the entire result.
Of the three runners you didn't touch, only one moved 30%+ from the open (+32.9%, and it didn't hold half of that by the close), so the opportunity cost sitting outside your 9 traded names was minimal.
Across the last week, halted runners held their moves far better than quiet ones: of 15 runners (including VCIG, RBNE, and CLRO from the 10/26-10/27 sessions) that saw at least one halt, 10 kept a positive share of their open-to-high move into the close, versus only 8 of 24 zero-halt runners managing the same. VCIG's 10-halt, 81%-retained session fits that holder pattern about as well as any name in the data; RBNE's single halt and -28% retention sits with the minority of halted names that faded anyway, which is consistent with you treating it as a quick in-and-out rather than a hold.
Your own lane data cuts directly against today's result. The 2+ halts/held 30 seconds or longer lane — your validated A+ tier at +$10 per $1k historically — produced 12 positions for -$1.60k today, all in VCIG.
The 4+ halts lane, a validated A tier at +$3.7 per $1k, gave you 19 positions and -$1.42k. Meanwhile the 2+ halts/scalped under 30 seconds lane, your validated DONT at -$3.4 per $1k, actually made +$187 on 7 positions today.
In short, the lanes that have paid you over ten months of data were the ones that lost money in this session, and the lane that has historically cost you money was the one that worked."}