2026-09-21 · 5 min read
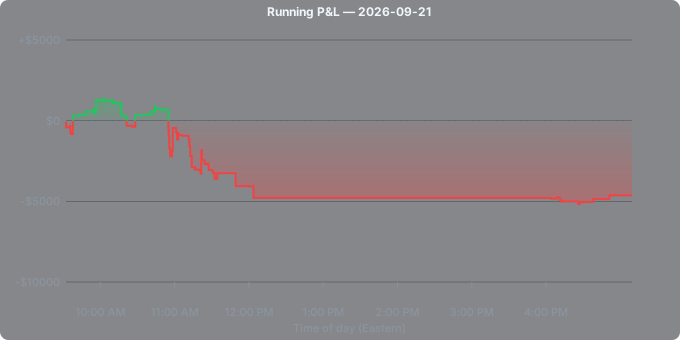
Session edge, AI coach verdict, and running P&L for 2026-09-21.
Trim Review
How much of today's result was carried by a few outliers? The table recomputes the core session stats with the biggest movers removed. Trimmed rows are colored vs baseline: green = holds most of the move, amber = meaningful erosion, red = collapses or flips sign.
| Scenario | Trades | Net P&L | Total R | E[R] / trade | $ WR | PF |
|---|---|---|---|---|---|---|
| Baseline (all trades) | 83 | −$4633.06 | -5.22R | -0.063R | 41.0% | 0.65 |
| − single best + single worst | 81 | −$4896.56 | -5.51R | -0.068R | 40.7% | 0.59 |
| − top 5 + bottom 5 (≈5% each tail) | 73 | −$6015.76 | -6.77R | -0.093R | 39.7% | 0.34 |
Trimmed trades: Single best + single worst — removed GRML +$1462.89 (best) · GRML −$1199.40 (worst). Top 5 + bottom 5 — removed 5 from each tail (by $ P&L).
Broad-based red session: the loss is still there after trimming the biggest movers — this wasn't one bad trade, it was the whole book tilted the wrong way.
Session verdict
GRML was the day's largest move and your largest concentration, and the two things did not line up. The stock opened at $7.330, ran to $11.68 by 11:21am (+59.3% from the open), and closed at $9.420, holding 48% of that move — a real, tradeable stock.
You ran 43 positions in it, 31 of your 43 entries before the 11:21am high, for -$5.94k gross. Your largest win, +$1.46k at 11:21am, landed at the exact top of the move, but your largest loss, -$1.20k at 10:54am, came 27 minutes earlier in the same stock, and the ledger shows a pattern of repeated re-entries into a name that eventually gave you money once and took it back many times over — 12 wins against 31 losses in one ticker is not a sizing story, it's a name that chopped you on the way to its high.
LOBO offered less magnitude but you handled it better: it opened at $0.7090, spiked to $1.290 by 10:02am (+81.9%) across four halts, then gave the whole move back to close at $0.7000, essentially flat on the day. You still netted +$676 gross across 19 positions, 10 wins to 9 losses, with your best entry at 9:56am catching +$829 near the highs before the reversal — extracting a real profit from a stock that ultimately returned to its open is the harder, more skillful outcome of the day.
BTTC (+$665 on 3 positions, entered ahead of its 10:29am high which held 45% of its move at the close) was a small but clean win in the same vein. VEEE was the mirror image of GRML: it moved +57.6% to $22.85 by 10:16am and held 33% of that at the close, but 4 of your 6 entries came after the high, and your worst loss of the position, -$746, came at 10:16am — the moment of the high itself — for a net -$195.
TOPS, CELZ and RUBI barely moved (0%, 4.8%, 5.9% from their opens respectively) and your late-day entries in them (all after any high there was to catch) produced small, proportionate results: +$221, +$33, -$97 — money made and lost in line with the size of the opportunity, which is the correct outcome for stocks that offered nothing.
Of the two runners you skipped today, neither moved 30% or more from the open (largest was +23.4%), so the opportunity cost sits near zero — you traded 7 of the 9 names that mattered and the two you left alone were the weakest movers on the list.
Across the trailing week, the largest-magnitude runners with heavy halt counts have been inconsistent holders — several stocks moving +330% or more with 20-plus halts each held anywhere from roughly a third of the move down to giving nearly all of it back, with no clean line separating the holders from the bleeders on float or halt count alone. GRML today, with zero halts, held 48% of a +59% move, while VEEE, with 3 halts, held only 33% of a similar-sized move, suggesting halt count itself isn't what determined retention here; your two biggest-dollar names this week don't fit a single retention profile, they split it.
Your own lane data shows a real split in how you traded volatility: the three positions with 2+ halts before entry held 30 seconds or longer — an A+ lane worth +11.0 per $1k over the study — cost you -$839 today, while the eleven positions with 2+ halts before entry that you scalped under 30 seconds — a DONT lane at -3.4 per $1k historically — cost -$819. The four sub-$1 scalps under 30 seconds, another validated DONT lane, cost a further -$45.
None of today's halt-based entries landed in your favorable lane in dollars, despite three of them sitting in the structure that lane describes.